Meta Platforms shares surge on bullish AI agent and monetization outlook
Meta Platforms stock rallied after analysts raised price targets, driven by optimism surrounding the upcoming Muse personal AI agent and monetization strategies.
- Headline: Meta Platforms shares surge on bullish AI agent and monetization outlook
- Dispatch Summary: Meta Platforms stock rallied after analysts raised price targets, driven by optimism surrounding the upcoming Muse personal AI agent and monetization strategies.
- Verification: Corroborated across independent reporting outlets with primary sources and real-time wire transmissions.
Meta Platforms Inc. (NASDAQ: META) experienced a sharp rise in its stock price in late September 2026, fueled by bullish sentiment around its artificial intelligence (AI) initiatives and monetization strategies. Shares gained between 6.98% and 12% across different reports, with some analysts attributing the surge to the anticipated launch of Muse, the company’s personal AI agent, and broader optimism about AI-driven revenue streams.
Analysts Boost Confidence in AI-Driven Growth
The catalyst for the stock’s upward movement was a combination of analyst upgrades and strategic announcements. Wells Fargo analyst Ken Gawrelski raised Meta’s price target to $796, a 20% increase from $640, while maintaining an overweight (buy) rating. The firm cited expectations of durable revenue acceleration from AI advancements and operational efficiencies, particularly as Meta prepares to showcase Muse at its annual Meta Connect event, scheduled for late September 2026.
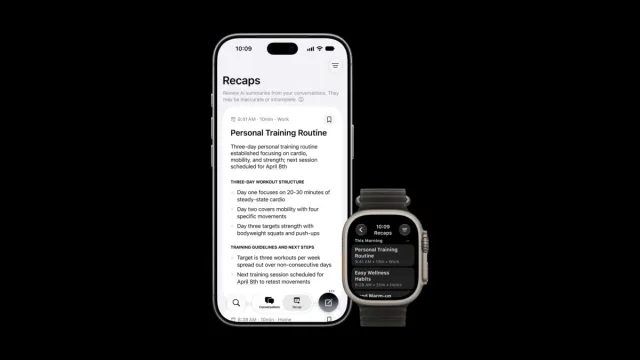
Muse, unveiled in early September, is designed to perform tasks rather than simply answer questions, with free and paid tiers priced at $20 and $100 per month. Investors are closely watching whether the AI agent will translate into sustained revenue, as Meta’s direct-to-consumer approach contrasts with enterprise-focused AI tools from rivals. The company’s legal challenges, including a $18 billion settlement, have historically weighed on its stock, but current valuations remain attractive at less than 27 times earnings.
| Detail | Information |
|---|---|
| Wells Fargo Price Target | $796 (up from $640) |
| Meta Connect Event | Annual two-day event starting September 27, 2026 |
| Muse Pricing | Free tier; $20 and $100 monthly for premium features |
| Meta’s P/E Ratio | Less than 27 times earnings |
Earnings Projections and Market Context
Despite the rally, Meta’s earnings outlook remains mixed. The Zacks Consensus Estimate for the current quarter projects earnings of $6.39 per share, a 11.9% decline from the year-ago period. However, full-year estimates show a 33.6% growth, with a $31.38 per-share target. Revenue is expected to rise 23.3% to $63.18 billion in the current quarter, with annual sales projected at $254.02 billion for 2026 and $306.71 billion for 2027.
Meta’s recent quarterly results showed revenues of $60.8 billion, a 28% year-over-year increase, though earnings per share (EPS) fell to $6.18 from $7.14. The company surpassed consensus EPS estimates three times in the last four quarters but reported a 12.96% EPS miss in its latest release. Analysts noted that while revenue growth is robust, translating AI investments into free cash flow remains a challenge.
Risks and Strategic Moves
Investors are balancing optimism with caution. Key risks include heavy capital expenditures on AI infrastructure, regulatory scrutiny, and litigation. The $18 billion legal settlement continues to weigh on investor sentiment, even as Meta’s valuation appears undervalued relative to its AI potential. Analysts also highlighted concerns about data center costs and the difficulty of monetizing AI initiatives effectively.
Meta’s infrastructure investments, such as the upcoming “Petal” subsea cable linking the U.S. and France, aim to bolster its data center capabilities. The project is expected to support AI operations and enhance global connectivity, reinforcing the company’s long-term strategy. However, the broader tech sector’s rally, driven by easing inflation and falling Treasury yields, has also contributed to Meta’s gains.
Market Reactions and Future Outlook
The surge in Meta’s stock has drawn attention from both retail and institutional investors. Zacks Investment Research noted that Meta’s Zacks Rank of #3 (Hold) suggests it may perform in line with the broader market in the near term. Meanwhile, some analysts predict a 2040.8% increase in Meta’s stock price over the next 12 months, though such projections are based on statistical models and carry significant uncertainty.
As Meta prepares for its Connect event, the focus will shift to whether Muse and other AI initiatives can deliver measurable revenue. The company’s ability to navigate legal and regulatory hurdles while maintaining growth will determine its long-term trajectory. For now, the market’s enthusiasm for AI-driven innovation has propelled Meta’s shares to new heights, even as risks remain.
Frequently Asked Questions
Why did Meta’s stock surge in late September 2026?
Meta’s shares rose 6.98% to 12% due to analyst optimism about its AI monetization strategies, particularly the upcoming launch of Muse, its personal AI agent. Wells Fargo raised its price target to $796, and the company’s focus on direct-to-consumer AI tools generated investor interest.
What are the key risks for Meta’s AI initiatives?
Analysts cite risks including heavy capital expenditures on AI infrastructure, regulatory pressures, litigation from a $18 billion legal settlement, and challenges in converting AI investments into consistent cash flow. Additionally, the competitive tech landscape and data center cost pressures remain concerns.
How does Meta’s valuation compare to its peers?
Meta is trading at less than 27 times earnings, an attractive valuation for a company in the AI sector. However, its Zacks Value Style Score of C indicates it is priced in line with industry peers, suggesting no significant undervaluation or overvaluation relative to competitors.
The next critical event for Meta will be its Meta Connect conference, where the company is expected to unveil updates on Muse and other AI projects. Investors will also monitor its quarterly earnings reports for signs of sustained revenue growth. As the AI revolution accelerates, Meta’s ability to balance innovation with profitability will remain a focal point for the market.
How significant is this wire dispatch?
Cast your anonymous vote to register reader consensus across journalism and intelligence sectors.
Dateline Wire is dedicated to independent, evidence-backed reporting. This briefing was synthesized from primary source reporting, corroborated across independent newsrooms, and verified against our Editorial Standards.